By Jesse Bravo | MktProFin
November 17, 2026
The LPL Financial Commonwealth conversion moved thousands of Commonwealth Financial Network representatives and their clients onto LPL’s technology and custody systems in one of the largest advisor platform conversions in the independent brokerage industry.
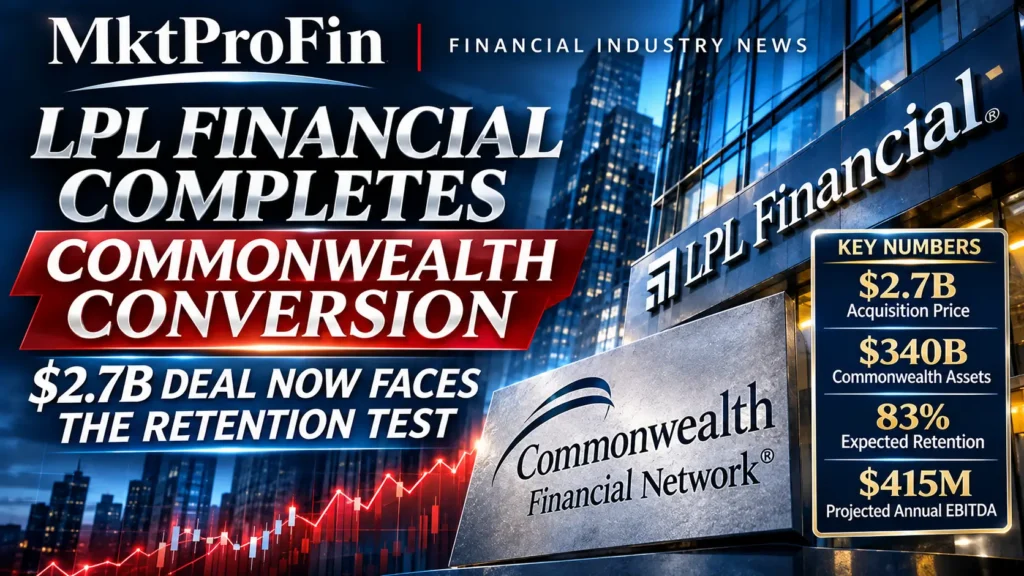
The conversion, completed over the November 14–15 weekend, marks a major milestone in LPL’s $2.7 billion acquisition of Commonwealth.
But completing the transition is only half the story.
LPL originally expected to retain 90% of Commonwealth’s client assets. That estimate has fallen to approximately 83%, raising questions about advisor departures, client retention and the financial return on the acquisition.
For investors, the real test begins now.
A $2.7 Billion Acquisition Reaches Its Most Critical Stage
LPL announced its agreement to acquire Commonwealth in March 2025 and completed the purchase on August 1 of that year.
Commonwealth brought approximately 3,000 financial advisors and a substantial wealth management business to LPL.
By September 30, 2026, Commonwealth’s client assets had grown to approximately $340 billion, according to LPL’s third-quarter investor presentation.
The acquisition gives LPL additional scale in an industry where technology, compliance expenses and advisor recruiting have become increasingly expensive.
LPL already operates one of the nation’s largest independent financial advisor platforms.
The company reported 32,597 advisors and approximately $2.6 trillion in client assets at the end of September.
Adding Commonwealth strengthens that position, although the amount of business retained will determine the acquisition’s ultimate contribution.
LPL Financial Commonwealth Conversion Is Complete. The Retention Question Remains.
LPL described the weekend conversion as successful.
Thousands of Commonwealth representatives moved onto LPL’s systems, replacing the technology infrastructure they had used for years.
InvestmentNews reported Monday that at least one Commonwealth advisor was waiting for client assets to appear in the new system.
That distinction matters.
A conversion can finish according to schedule while individual advisors continue working through account displays, operational questions and client service adjustments.
For financial advisors, access to accurate client information is essential.
Even temporary difficulties can affect trading, reporting and client confidence.
The more significant concern involves retention.
LPL initially projected it would keep 90% of Commonwealth’s assets. By its October earnings presentation, the company had reduced that estimate to 83%.
Applied to Commonwealth’s approximately $340 billion in September assets, a seven-percentage-point difference represents roughly $23.8 billion.
That calculation illustrates the scale of the change in expectations. It is not a confirmed post-conversion asset loss.
Actual retained assets will depend on final advisor decisions, client transfers and market movements.
Why Commonwealth Advisors Were Attractive to Competitors
Commonwealth built its reputation around personalized service, advisor independence and technology designed for financial professionals.
Those characteristics made its advisors attractive recruiting targets.
Following the acquisition announcement, competing brokerage firms began approaching Commonwealth representatives concerned about losing the service model they had chosen.
Raymond James, Kestra Financial and other competitors pursued advisors during the transition period.
Some advisors decided to leave rather than move to LPL.
Others remained, attracted by LPL’s financial resources, investment capabilities and broader technology infrastructure.
The competition illustrates a fundamental reality of independent wealth management.
Financial advisors can move their practices, and their clients often have the opportunity to follow.
An acquisition does not guarantee that the buyer retains every relationship.
For LPL, preserving Commonwealth’s service culture could prove as important as completing the technology conversion.
LPL Expects $415 Million in Annual EBITDA
Despite lower retention expectations, LPL continues to project substantial financial benefits.
Its third-quarter investor presentation estimates that Commonwealth will generate approximately $415 million in annual run-rate EBITDA after integration.
That compares with acquired baseline EBITDA of approximately $90 million.
The difference reflects expected revenue improvements and operating efficiencies, rather than profits already realized.
LPL estimates approximately $485 million in onboarding and integration expenses, plus $215 million in technology investment that will be capitalized and amortized.
Those costs demonstrate how expensive large brokerage integrations can become.
The company expects to benefit from its scale, including revenue opportunities associated with client cash, investment products and existing business relationships.
Expense savings could take longer.
LPL has indicated that it intends to preserve Commonwealth’s service organization, limiting the immediate cost reductions available through consolidation.
The financial question is whether future earnings justify the acquisition price and integration spending.
What the Deal Means for LPL Shareholders
For shareholders of LPL Financial Holdings, which trades on Nasdaq under LPLA, the Commonwealth acquisition creates both opportunity and risk.
The opportunity comes from additional client assets, advisor relationships and potential operating efficiencies.
LPL can spread technology and compliance investments across a larger advisor population.
It can also pursue additional revenue from services offered through its platform.
The risk comes from integration expenses, advisor departures and lower-than-expected asset retention.
A large acquisition can increase reported assets while producing disappointing financial returns if the cost of acquiring and servicing those assets becomes excessive.
Investors should therefore examine organic asset growth separately from acquisition-related growth.
They should also monitor operating margins, adjusted earnings, integration expenses and the timing of projected savings.
The approximately $415 million EBITDA target is particularly important.
If LPL achieves that figure, the acquisition could become a meaningful contributor to earnings.
If retention weakens further or expenses exceed expectations, the financial outcome could disappoint.
Independent Broker-Dealers Face Greater Consolidation Pressure
The Commonwealth transaction reflects a broader shift in wealth management.
Independent brokerage firms face rising expenses associated with cybersecurity, regulatory compliance, technology and advisor support.
Larger organizations can distribute some of those costs across thousands of representatives.
Smaller competitors must find ways to offer comparable services without the same financial resources.
That creates pressure to merge, sell or develop specialized business models.
But size alone does not determine success.
Independent advisors frequently place substantial value on responsive service, operational flexibility and control over client relationships.
A larger platform that fails to deliver those qualities can create opportunities for competitors.
Commonwealth’s integration will therefore serve as an important test of whether LPL can combine institutional scale with the service experience independent advisors expect.
What Wall Street Should Watch Next
The next several quarters will provide a clearer picture of the acquisition’s financial performance.
Investors should focus on final asset retention, advisor departures, client transfers and progress toward the projected $415 million annual EBITDA contribution.
LPL’s fourth-quarter results will be especially important because they will provide the first financial reporting period following the conversion.
Management will also need to demonstrate that Commonwealth advisors can operate efficiently on the new platform without sacrificing client service.
Completing the conversion removes a major operational obstacle.
It does not eliminate the commercial risks associated with the acquisition.
LPL has successfully moved a substantial brokerage business onto its infrastructure.
Now it must prove that the advisors, assets and earnings expected from the transaction will remain.
For Wall Street, the question is no longer whether LPL can complete the Commonwealth conversion.
It is whether the $2.7 billion acquisition will deliver the financial return investors were promised.
Sources: LPL Financial third-quarter 2026 investor presentation, InvestmentNews, Citywire RIA, WealthManagement.com, Financial ADVSR.
MktProFin | Financial Markets, Wealth Management and Industry Analysis.